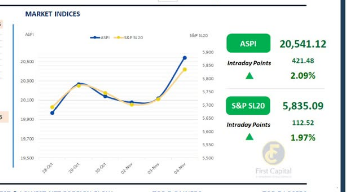
The Colombo Bourse continued its upward trajectory from the previous session, with a notable increase in market activity and turnover today. The ASPI surged 421 points to close at 20,541, while the S&P SL20 gained 113 points to close at 5,835, reflecting strong gains across both indices.
Investor participation strengthened considerably, with both retail and HNW segments recording elevated activity and contributing almost equally to the turnover. The improved sentiment may have been supported by optimism surrounding the midterm elections, while the sharp increase in turnover reflected renewed investor interest in the market.
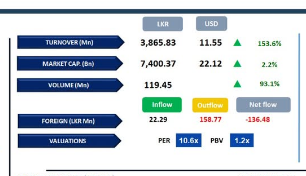
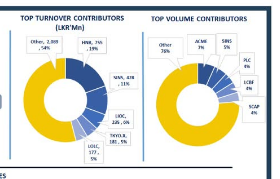
Daily turnover stood at LKR 3.9Bn, marking an increase of 173.3% over the monthly average of LKR 1.4Bn. Banking sector led the daily turnover with a share of 25%, followed by the Materials, and Diversified Financials sectors collectively contributing 30%. Foreign investors remained net sellers, posting a net outflow of LKR 136.5Mn.
BOND MARKET
Yield curve eases following us midterms amid improving geopolitical sentiment
Following the conclusion of the US midterm elections, in which the Democrats secured victories in both chambers of Congress, global oil prices eased to around USD 100/bbl, providing some relief on the geopolitical front.
The improved external environment contributed to relatively higher market activity, although investor sentiment remained somewhat mixed amid lingering uncertainties surrounding the domestic interest rate outlook.
Despite this cautious sentiment, market rates continued to trend lower, supported by domestic investor demand. Foreign selling was particularly evident in the 2032, 2033 and 2034 maturities; however, these positions were absorbed by domestic investors.
Within the 2030 maturity segment, 15.05.2030, 01.08.2030 and 15.10.2030 traded within a range of 11.40%–11.55%. Moving further along the curve, 01.02.2031 traded at 11.60%, while 01.12.2031 recorded trades at 11.75%.
The 15.12.2032 maturity, which witnessed foreign selling, traded at 12.00%. In the 2033 segment, both 01.06.2033 and 01.11.2033 traded at 12.35%. Further along the curve, 15.10.2034 traded within a range of 12.49%–12.45%, while the 15.08.2036 maturity recorded trades within a range of 12.80%–12.75%.
Today, the PDMO concluded its weekly T-Bill auction, raising LKR 65.9Bn, below the initial offer amount of LKR 90.0Bn. For the 3M T-Bill, LKR 40.0Bn was initially offered, while LKR 53.9Bn was accepted. The weighted average yield rate (WAYR) increased by 1bp to 9.35%. For the 6M T-Bill, the PDMO accepted only LKR 6.6Bn against an offered amount of LKR 30.0Bn, with the WAYR remaining unchanged at 9.44%.
For the 12M T-Bill, LKR 5.4Bn was accepted, which was below the offered amount, while the WAYR remained unchanged at 9.95%. On the external front, the LKR stood flat at LKR 332.6/USD. Market liquidity in the banking system expanded marginally to LKR 389.73Bn compared to LKR 389.68Bn seen previously.
-First Capital Research-
Subscribe to our newsletter to get notification about new updates, information, etc..