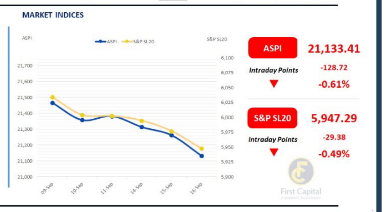
The Colombo Bourse remained under pressure today, with selling sentiment continuing amid elevated global oil prices and concerns over a potential increase in interest rates.
These concerns continued to weigh on investor sentiment limiting buying interest across the market. The ASPI fell 129 points to close at 21,133 while the S&P SL20 fell 29 points to close at 5,947, both indexes reflecting the broader negative sentiment.
Top negative contributors to the ASPI were JKH, CINS, BREW, MELS and RIL. Turnover continued to remain low, with retail and HNW investors contributing broadly in line with average levels. However, HNW participation was above average and was particularly concentrated in conglomerate counters.
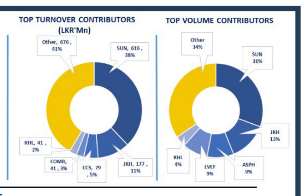
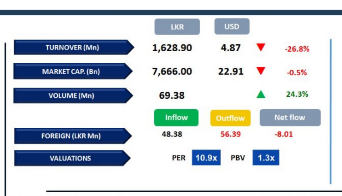
Daily turnover stood at LKR 1.6Bn, marking a decrease of 33.1% over the monthly average of LKR 2.4Bn. Food Beverage & Tobacco sector led the daily turnover with a share of 48%, followed by the Capital Goods, and Banking sectors collectively contributing 25%. Foreign investors remained net sellers, posting a net outflow of LKR 8.0Mn.
BOND MARKET
T-Bill auction yields edge higher across the board
Secondary market activity remained active, with high trading volumes and moderate activity amidst continued selling pressure concentrated around the 2030 to 2033 maturity bracket at the belly of the curve.
Consequently, yields moved higher across the curve, with the belly witnessing a relatively sharper upward movement. Starting at the short end, the 15.09.2029 and 01.03.2030 maturities traded at 11.00%.
Moving on to the 2030 segment, 01.07.2030, 01.08.2030 and 15.10.2030 maturities traded from 11.40% to 11.55%. Moving along the curve, 01.02.2031 maturity traded from 11.60% to 11.65%. The 15.01.2033 and 01.11.2033 bonds traded from 11.95% to 11.96%. The 15.09.2034 and 15.10.2034 maturities traded at 12.16% and 12.10% respectively, whilst 15.03.2035 and 15.08.2036 traded at 12.20% and 12.16% respectively.
Furthermore, 01.07.2037 maturity traded at 12.20%. Today, the PDMO concluded its weekly T-Bill auction, raising LKR 70.0Bn, in line with the total amount initially offered. For the 3M T-Bill, LKR 25.0Bn was offered, against bids totalling approximately LKR 63.4Bn. The weighted average yield increased by 15bps to 9.18% for 3M maturity. The PDMO accepted the full LKR 25.0Bn offered for the 6M T-Bill, with the weighted average yield rising by 12bps to 9.36%.
For the 12M T-Bill, the full LKR 20.0Bn offered was accepted, while the weighted average yield increased by 11bps to 9.88%. On the external front, the LKR depreciated against the USD, standing at LKR 330.18/USD, compared to LKR 329.04/USD seen earlier. Market liquidity in the banking system contracted to LKR 336.44Bn compared to LKR 347.55Bn recorded previously.
First Capital Research
Subscribe to our newsletter to get notification about new updates, information, etc..