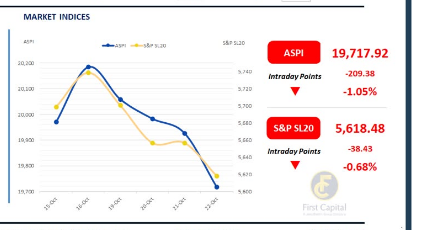
Negative sentiment gripped the CSE, with panic selling weighing on investor confidence and dragging the broader market lower. The ASPI plunged 209 points to close at 19,718, whilst the S&P SL20 shed 38 points to end at 5,618.
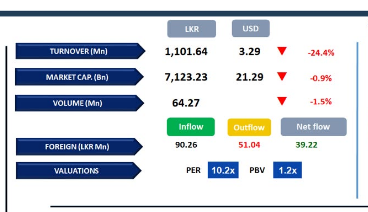
The top negative contributors to the index were DIST, HNB, DIAL, SINS and CARS. Amidst the prevailing selling pressure, heightened activity in blue-chip counters, including JKH and SUN, alongside crossings in SAMP and COMB, supported turnover, which stood at LKR 1.1Bn.
However, this stands approximately 17.9% below the monthly average of LKR 1.3Bn, reflecting subdued participation from both retail and HNW investors amid heightened market uncertainty.
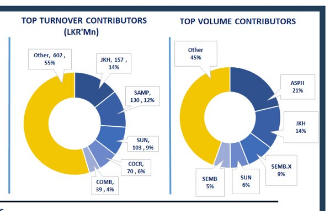
The Banking sector accounted for the largest share of turnover at 23%, followed by the Capital Goods, and Food, Beverage & Tobacco sectors, which jointly contributed 39%. Foreign investors turned net buyers, accounting for a net inflow of LKR 39.2Mn.
BOND BARKET
Geopolitical woes weigh down on the secondary market
Overall investor sentiment turned mixed today as persistent geopolitical tensions weighed down on the secondary market. Transactions and trading volumes were limited amid constrained investor participation.
Noteworthy activity was largely clustered around mid-tenors with, 01.08.2030 and 15.10.2030 trading within a narrow range of 11.58% to 11.60%.
Further along the curve 01.02.2031 and 01.12.2031 traded at 11.75% and 11.85% respectively. Towards the belly end of the curve 15.06.2034 and 15.10.2034 both traded at 12.45% while 15.03.2035 traded higher at 12.55%.
On the external front, the LKR marginally depreciated against the USD, standing at LKR 331.91/USD, compared to LKR 331.75/USD seen earlier. Market liquidity in the banking system expanded marginally to LKR 380.98Bn compared to LKR 379.13Bn recorded previously.
-First Capital Research
Subscribe to our newsletter to get notification about new updates, information, etc..