After 5 consecutive days of losses in the Colombo Bourse, today the market saw a reversal in the investor sentiment, weighing on the drop in global oil prices.
Although the global oil market was volatile, the Bourse sustained its positive momentum through most of the session, further backed by the positivity stemmed from CBSL’s decision yesterday to maintain the OPR at 8.75%.
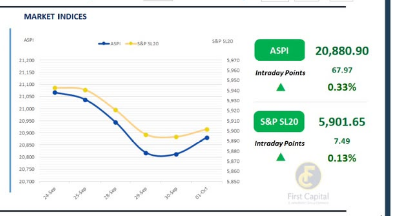
By the end of the day, the ASPI gained 68 points to close at 20,881, while the S&P SL20 also gained 7 points to close at 5,902. The top positive contributors to the ASPI index were DIAL, SINS, LION, CARS, and LOLC.
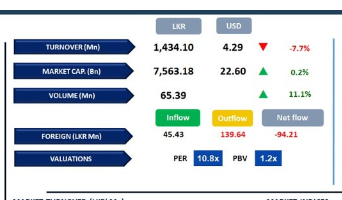
Turnover was largely contributed by HNW investors, whose interest was predominantly seen across the Banking sector. However, the retail investors depicted a low participation. Daily turnover stood at LKR 1.4Bn, marking a slight decrease of 2.1% over the monthly average of LKR 1.5Bn.
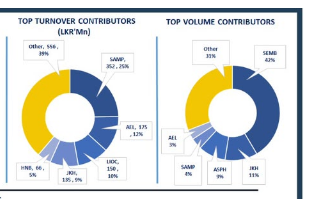
Banking sector led the daily turnover with a share of 34%, followed by the Capital Goods, and Energy sectors collectively contributing 40%. Meanwhile, foreign investors remained net sellers, posting a net outflow of LKR 94.2Mn.
BOND MARKET
Mixed sentiment keeps the yield curve broadly unchanged
The secondary bond market yield curve saw mixed sentiment amid limited activity and low volumes, keeping the yield curve broadly unchanged.
Among the trades recorded today, at the short end of the curve, the 15.10.2029 and 15.12.2029 maturities traded within the range of 10.75% to 10.85%, while the 01.08.2030 and 15.10.2030 maturities traded between 11.12% to 11.20%.
Within the 2031 segment, 01.02.2031 traded at 11.25%, while 15.12.2032 traded at 11.70%. Further along the curve, the 15.01.2033 and 01.11.2033 maturities traded at 11.75% and 11.85%, respectively.
Meanwhile, the 15.06.2034 and 15.09.2034 traded within the range of 12.00% to 12.05%, while the 15.06.2035 traded at 12.10%. On the external front, the LKR appreciated marginally against the USD, standing at LKR 330.70/USD, compared to LKR 330.83/USD seen earlier.
Market liquidity in the banking system expanded to LKR 355.13Bn compared to LKR 338.66Bn recorded previously. Additionally, the external current account recorded a surplus of USD 133.4Mn in Aug-26, following four consecutive months of deficits.
The improvement was mainly supported by a lower trade deficit, driven by lower import expenditure. However, the current account recorded a cumulative deficit of USD 290.6Mn during Jan to Aug 2026, reflecting continued external sector pressures amid the escalation of the Middle East conflict.
-First Capital Research-
Subscribe to our newsletter to get notification about new updates, information, etc..